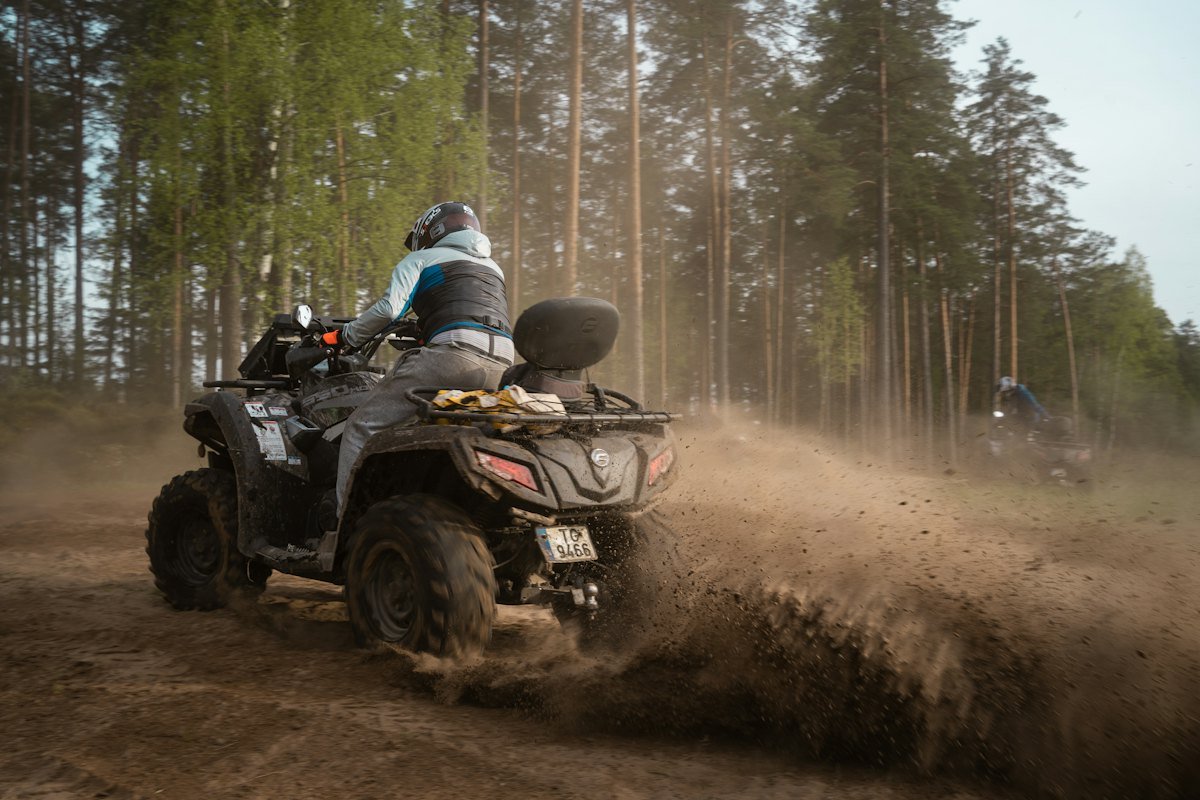
Do you even need a policy for a four-wheeler? For a quad that never leaves your own land, maybe not; for one that rides public trails or carries a loan, almost certainly. Coverage is cheap by vehicle standards: ValuePenguin’s sample quotes average about $88 a year for liability only and $327 a year for full coverage, with individual insurers ranging from $61 to $510. GEICO’s ATV coverage guide adds the detail many owners miss: once you ride off your land or trailer the machine to a park or trail, homeowners coverage typically stops.
Which end of that range you land on depends less on the machine than on how you use it. So instead of one national average, we priced four riders for 2027: a farm quad that never leaves home, a paid-off trail machine, a brand-new financed Honda, and a family with a teenager in the saddle.
| Rider | What they actually need | Typical yearly premium |
|---|---|---|
| Farm or chore quad, own land only | Often no state requirement; check what the home or farm policy excludes | $0 to about $88 for basic liability |
| Paid-off machine on public trails | Liability, usually required by the trail or state | $61 to $126 for liability only |
| New machine with a loan | Liability plus comprehensive and collision, set by the lender | $165 to $510 for full coverage |
| Household with a teen rider | Same as above, with every rider listed and eligible | Higher than adult-only quotes; no published average |
Source: premium ranges from ValuePenguin’s ATV insurance cost study (updated June 30, 2026), based on sample quotes for a 30-year-old Wisconsin rider. Your price will differ by state, machine and history.
Rider one: the chore quad that stays on the farm
Picture a utility ATV that hauls feed, drags a small harrow and sleeps in the barn. It never crosses a public road or a state trail. For this owner, the law usually asks for little. New York’s DMV requires liability insurance to operate an ATV anywhere in the state except on your own property, and machines used only for agriculture are exempt from registration. Pennsylvania’s DCNR offers a free limited registration that never expires for on-property use, and requires liability insurance only when you ride land you do not own or lease.
The legal minimum is not the same as being covered, though. Homeowners policies treat off-road vehicles narrowly, and some exclude them outright. Progressive notes that a homeowners policy’s personal liability portion may offer some protection if a guest is hurt riding on your property, but that is the extent of it in most cases. If the quad rolls into a creek or disappears from an unlocked shed, the home policy is unlikely to pay for the machine.
The decision for rider one comes down to two questions for your agent: does my home or farm policy cover injuries a guest suffers on my ATV, and does it cover the ATV itself against theft? If either answer is no, a liability-only ATV policy at roughly $88 a year, with comprehensive added for theft, is inexpensive protection for a machine worth thousands.

Rider two: a paid-off machine and public trail weekends
Our second rider owns a seven-year-old quad outright and trailers it to state forest trails most summer weekends. No lender is asking for anything, and the machine might sell for a few thousand dollars. Liability is the coverage that matters here, because the expensive risk on a shared trail is hurting someone else, not denting your own fenders.
Many riders need it anyway. GEICO notes that ATV insurance may be required in state-owned or public parks, and Progressive says liability can be mandated at certain private trails and parks. In Pennsylvania, riders on land they do not own must carry proof of liability insurance, though the state sets no minimum limits. In New York the registration itself is only $12.50 a year, but the machine still needs liability coverage the moment it leaves your land.
Liability-only premiums in ValuePenguin’s sample ran from $61 a year with Markel to $126 with Allstate. Insurify’s 2026 comparison quoted a different sample rider, a 28-year-old in Madison with a 2022 Polaris Sportsman, at $18.50 a month with Progressive and $49 a month with Allstate. That gap between two studies of similar riders is itself the lesson: quotes swing widely, so collect at least three.
Should rider two skip collision and comprehensive? Usually, yes. If the machine is worth $3,000 and the deductible is $1,000, a full-coverage policy that costs $200 or more extra each year needs a bad crash or a theft every few years to pay off. Keep the money in savings and buy higher liability limits instead.
Rider three: a new $10,369 Rubicon on a payment plan
The third rider just bought a 2026 Honda FourTrax Foreman Rubicon 4×4 EPS, which Honda lists at a $9,749 base MSRP plus a $620 destination charge, or $10,369 before dealer fees and tax. With a loan on the machine, the coverage choice is no longer entirely theirs: lenders typically require comprehensive and collision for as long as they hold the title.
Full coverage in ValuePenguin’s study averaged $327 a year, with Dairyland lowest at $165 and Allstate highest at $510. That sample used $500 deductibles on both collision and comprehensive, the lower of the two options GEICO offers. Choosing a $1,000 deductible usually trims the premium, but make sure you could cover it the week after a crash.
Two add-ons deserve a look on a new machine. Progressive’s ATV insurance overview says its policies with comprehensive and collision automatically include $3,000 of accessories and custom parts coverage, which can be raised to $30,000 for owners who add winches, plows, racks or upgraded wheels. Financed buyers should also ask about GAP coverage, which pays the difference between what you owe and what the machine is worth if it is totaled early in the loan.
Same rider, six insurers: how far apart the quotes land
One quote tells you almost nothing. The ValuePenguin sample held the rider, machine and limits constant and still found the most expensive insurer charging three times the cheapest for full coverage.
| Insurer | Liability only, per year | Full coverage, per year |
|---|---|---|
| Markel | $61 | $352 |
| GEICO | $70 | $421 |
| Progressive | $75 | $188 |
| Dairyland | $106 | $165 |
| Allstate | $126 | $510 |
| Average | $88 | $327 |
Source: ValuePenguin sample quotes for a 30-year-old man in Green Bay, Wisconsin, on a 2021 Honda FourTrax Rubicon with 50/100/25 liability limits and $500 deductibles.
Notice that the cheapest liability carrier is not the cheapest full-coverage carrier. Dairyland was the second most expensive for liability yet the least expensive for full coverage, while Markel, cheapest for liability, landed mid-pack for full coverage. Price the exact coverage you plan to buy, not a teaser quote for a different package.
Rider four: a household where a teenager rides too
This is where cheap policies quietly fail. Insurify warns that if an underage rider takes your ATV out and something happens, your insurer won’t cover it. GEICO says rates for teen riders can run higher because of limited experience, though no insurer publishes a typical surcharge.
Machine size matters as much as the policy. Honda recommends the Rubicon only for riders 16 and older, and the Consumer Product Safety Commission says riders younger than 16 should drive only age-appropriate youth models, never adult ATVs. In New York, 14- and 15-year-olds may ride only under adult supervision or in limited settings such as land owned by a parent.
To price a family policy honestly, do it in this order:
- List every rider by name and age on the application, including occasional riders such as visiting cousins.
- Match each rider to a machine the manufacturer rates for their age; an adult ATV ridden by a 12-year-old is both a safety and a coverage problem.
- Ask about safety-course credit. Progressive offers a discount for completing an ATV safety course within the past three years.
- Raise medical payments coverage if your health plan has a high deductible, since injured passengers and riders are the likeliest claims.
- Get the eligibility rules in writing, so you know who may ride before a claim, not after.
What the coverage pays for when a ride goes wrong
ATV premiums are low partly because riders log few miles, but the claims that do happen tend to involve injuries rather than fender-benders. That is why liability limits and medical payments coverage carry more weight in an ATV policy than the price of the machine suggests.
CPSC data show an annual average of more than 800 deaths and an estimated 100,000 emergency department-treated injuries involving off-highway vehicles, with ATVs in more than two-thirds of the deaths.
U.S. Consumer Product Safety Commission

A typical ATV policy, as GEICO describes it, combines bodily injury and property damage liability, collision, comprehensive, medical payments in most states, and uninsured or underinsured motorist coverage. ValuePenguin’s sample used 50/100/25 liability limits: $50,000 per injured person, $100,000 per accident and $25,000 for property damage. A single serious trail injury can exceed that, and stepping up limits usually costs far less than adding physical damage coverage. Homeowners with an umbrella policy should ask whether it extends to recreational vehicles; many require the underlying ATV policy to carry specific limits first.
For 2027, nothing announced changes the math. Neither New York’s $12.50 annual registration nor Pennsylvania’s $20 two-year general registration lists an update for next year, and ATV rates are filed insurer by insurer, so watch your renewal notice rather than headlines.
Four riders, one rule for buying the policy
Buy liability for any ATV that leaves your land, because the law or the trail often requires it and the premium is small. Add comprehensive and collision only when a lender demands it or the machine is worth more than you could replace from savings. Before anyone under 16 rides, confirm in writing that the policy covers them on that specific machine. And collect three quotes, because the same rider in the same study paid anywhere from $165 to $510 for identical full coverage.
Leftover questions from ATV owners
How much is ATV insurance a month?
In ValuePenguin’s sample, liability-only coverage averaged about $88 a year, or roughly $7 a month, and full coverage about $327 a year, or roughly $27 a month. Insurify’s separate sample quoted Progressive at $18.50 a month for liability. Paying the full year at once can earn a discount with some insurers.
Is side-by-side or UTV insurance priced the same way as ATV insurance?
The coverage types are the same, and insurers such as GEICO and Progressive write both on similar policies. Insurers price each machine on its value, engine size and use, so get a separate quote rather than assuming an ATV price carries over.
Will any insurer cover a three-wheeler or a small youth ATV?
Not every one will. GEICO says it insures most four-wheel ATVs and side-by-sides but not three-, six- or eight-wheel machines or ATVs and UTVs under 150cc. Specialty insurers and local agents are the place to ask about those.
What discounts lower ATV insurance cost?
Progressive lists discounts for paying in full, completing an ATV safety course within the past three years, bundling with a home or car policy, and insuring several ATVs on one policy. Other insurers add credits for anti-theft devices and claim-free history.
Which deductible should I choose for ATV insurance?
GEICO offers $500 or $1,000 deductibles on collision and comprehensive. The higher deductible lowers the premium; pick it only if you could pay $1,000 out of pocket without strain.
The pages behind these numbers
- ATV Insurance: What Does It Cover and How Much Is It?, ValuePenguin (updated June 30, 2026)
- Cheapest ATV Insurance Companies (2026), Insurify (updated November 10, 2025)
- ATV Insurance Coverage Information, GEICO (August 31, 2026)
- What is ATV insurance?, Progressive (updated October 5, 2023)
- Register an ATV, New York State Department of Motor Vehicles
- Register or Title Your ATV, Pennsylvania Department of Conservation and Natural Resources
- 2026 FourTrax Foreman Rubicon 4×4 EPS, Honda Powersports
- OHV & ATV Safety, U.S. Consumer Product Safety Commission
Insuring the rest of your toys and vehicles
- The complete 2027 guide to insurance, legal and real estate costs
- Motorcycle insurance cost, myths tested
- Boat insurance cost and the traps to avoid
- Camper insurance versus your auto policy
- Homeowners insurance cost and the dials you control
- How much auto insurance costs
More related guides: Dirt bike prices with gear and upkeep
Pricing method: premiums and fees were researched in November 2026 for 2027 planning and may change. Insurance quotes depend on your state, machine, riders and history, so confirm coverage and eligibility with a licensed agent or insurer. This is general information, not insurance advice. See our disclaimer.