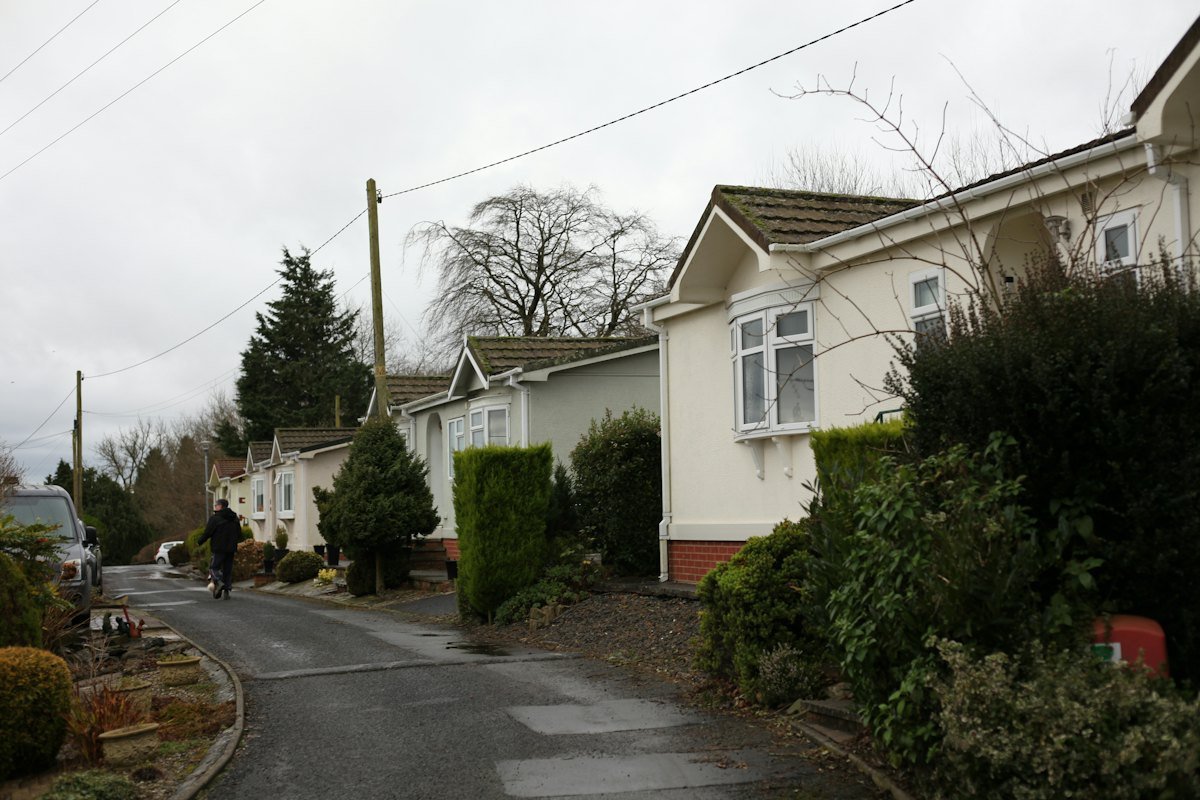
On July 11, 2026, Congress rewrote the federal definition of a manufactured home. The 21st Century ROAD to Housing Act drops the old rule that every one must be built on a permanent steel chassis, a change Rep. Kathy Castor described to Spectrum News as removing “that very expensive chassis system.” None of it has reached the sales lot yet. The average new single-section home sold for $80,900 in June 2026 and the average double-section for $162,900, according to Census Bureau survey data published through FRED, and those prices exclude land, site work and a single month of lot rent.
That last item is why the sticker price misleads. A manufactured home is the cheapest new house in America to buy and one of the trickier ones to own, because where it sits and how it is titled shape the next ten years of payments more than the model you pick. This guide prices the house, then follows the money for a decade. If you are comparing it with a site-built or modular home, our house and barndominium cost calculator gives you the other side of the ledger.
The sticker price, by number of sections
Manufactured homes are priced by how many factory-built boxes arrive on the truck. Census averages move month to month (the single-section figure was $90,700 in March 2026 and $80,900 by June), so treat them as a midpoint, not a quote.
| Home type | Typical size | Average new price | Source and date |
|---|---|---|---|
| Single-section (single-wide) | 600 to 1,300 sq ft | $80,900 | Census via FRED, June 2026 |
| Double-section (double-wide) | 1,000 to 2,400 sq ft | $162,900 | Census via FRED, June 2026 |
| Triple-section | 2,000 to 3,400 sq ft | From about $200,000 | SoFi, May 2026 |
| Resale mobile home listing, land included | Varies | $150,000 median | Realtor.com, September 2026 |
For scale, SoFi sets the double-wide average against $419,200 for a new single-family house. Regional prices also differ: the Census average for all new manufactured homes in the South was $139,900 in March 2026. Ask in writing what the dealer’s quote includes, because porches, steps and driveways usually are not part of it.
Land is the line that splits the 10-year bill
Every buyer lands in one of two camps. Either the home goes on a rented lot in a land-lease community, or it goes on ground you own. The first is cheaper on day one. The second costs more up front and usually less to finance, and it leaves you holding an asset that includes dirt.
Placing a home on raw land means paying for the utilities a park already has. SoFi’s national ranges:
- Water line or well: $5,000 to $15,000
- Septic system: $3,500 to $15,000
- Electric service: $2,500 to $12,500, and $10,000 or more in some areas
That is $11,000 to $42,500 before a driveway, which SoFi prices at $3,460 to $6,910, or a deck at $9,000 to $20,000. A land survey belongs on the list too if the parcel has never been staked. And if you still need the land itself, our guide to what an acre costs shows why buildable lots are priced so differently from raw acreage.
Lot rent: the payment that never ends and rarely stays put
SoFi puts typical lot rent at $200 to $800 a month, before any HOA-style fees. The trouble is not the starting number but the slope. Investors have been buying communities, and local reporting through 2026 shows what follows a sale:
Lot rent at one College Station community went from $295 in December 2024 to $630 by April 2026.
KBTX, February 2026
It is not an isolated case. In Tomah, Wisconsin, one resident told News 8000 her rent went from $265 to $525. In Centre County, Pennsylvania, Spotlight PA reported a household whose payment rose from $405 to $535 after a new owner added a base-rent increase plus new trash and sewer charges, and a Lehigh County resident whose rent had nearly doubled to almost $900. Pennsylvania’s House passed a bill in June 2025 that would hold most increases between 2% and 4% a year, but it has sat in a Senate committee since.
The reason this matters more than an apartment rent hike: you own the home but not the ground, and moving it is expensive. Spotlight PA cited a $6,000 quote to move a home less than a mile. Read the community’s rent history and lease terms before you read the floor plan.
Chattel loan or mortgage: how the title changes the money
A home on a rented lot is usually financed with a chattel loan, secured by the home alone, much like a car loan. The Consumer Financial Protection Bureau found that about 42% of manufactured home purchase loans are chattel loans and that they carry higher interest rates and fewer consumer protections than mortgages. A home permanently installed on land you own can often be titled as real estate and financed with a conventional, FHA, VA or USDA mortgage instead.
FHA’s separate Title I program also lends on manufactured homes, including ones on leased lots. Its limits were raised in 2024 for the first time in about 15 years, for case numbers assigned from March 29, 2024:
| FHA Title I loan type | Limit |
|---|---|
| Home only, single-section | $105,532 |
| Home only, multi-section | $193,719 |
| Lot only | $43,377 |
| Home and lot, single-section | $148,909 |
| Home and lot, multi-section | $237,096 |
Two buyers, ten years, one ledger
To show how land and financing play out, here are two hypothetical buyers. The home prices are the June 2026 Census averages. Every other input is an assumption labeled as such, not a quote, and property taxes, utilities and maintenance are left out because they vary too much by county to average honestly.
- Buyer A puts an $80,900 single-wide in a land-lease community. Lot rent starts at $550 and rises 4% a year. She puts 10% down and takes a 20-year chattel loan at an illustrative 9%.
- Buyer B puts a $162,900 double-wide on land he already owns, spends an illustrative $25,000 on well, septic and power, and finances the home with a 30-year mortgage at 7.4% with 5% down, the rate Realtor.com used in an October 2026 example.
| 10-year line item (example) | Buyer A: single-wide, rented lot | Buyer B: double-wide, owned land |
|---|---|---|
| Down payment | $8,090 | $8,145 |
| Utility hookups, paid in cash | $0 (park supplies them) | $25,000 |
| Loan payments over 120 months | $78,611 ($655 a month) | $128,579 ($1,071 a month) |
| Lot rent over 10 years | $79,240 (ends near $783 a month) | $0 |
| Insurance (about $1,000 vs $1,300 a year) | $10,000 | $13,000 |
| Cash out the door | $175,941 | $174,724 |
| Loan balance still owed | $51,714 | $134,022 |
| What they own at year 10 | A 10-year-old home on someone else’s land | A 10-year-old home plus the land, titled together |
The cash nearly ties, which surprises most people. Buyer A’s house costs half as much, but lot rent quietly equals her entire loan payments. Buyer B owes more at year 10, yet his debt is backed by real property he controls, and no landlord can raise his ground rent. If Buyer A’s park sold and her rent followed the College Station path, her 10-year column would grow by tens of thousands of dollars. The single-wide only clearly wins when the lot rent is low and protected, as in a resident-owned community or a state with rent limits.
Costs that show up after move-in day
Insurance. ValuePenguin’s July 2026 analysis puts mobile home policies anywhere from under $1,000 to nearly $2,500 a year, and location drives it: the same $63,000 single-wide averaged $969 a year to insure in Indianapolis and $1,607 in Austin. Get quotes from specialty carriers as well as your auto insurer; our homeowners insurance guide covers the deductibles and discounts that move a premium.
Taxes. SoFi notes that dealer purchases may carry sales tax, and owners of the land pay annual property tax. A home titled as personal property is taxed differently from real estate in many states. Ask your county assessor which applies before you compare monthly budgets.
Upkeep below the floor. Skirting, tie-downs, piers and the vapor barrier all need checking, and a lender may require an engineer’s foundation letter at resale or refinance. Our foundation inspection guide prices that letter.
What if I ever need to move the home?
Budget for it as a real possibility in a land-lease community. Residents quoted in 2026 news coverage cited $6,000 for a move of under a mile in Pennsylvania and $10,000 in Wisconsin, before the new site’s setup. Many owners in a rent dispute find selling in place cheaper than moving; our mobile home moving cost guide runs both numbers.
What the 2026 housing law does and does not change for 2027 buyers
The ROAD to Housing Act lets homes be built with or without a permanent chassis and, as Inman summarized it, requires chassis-free homes to be treated the same as chassis-built ones for financing, titling, insurance, taxes, transport and installation. States get one year after enactment to update their own laws, or two years where the legislature meets every other year, so many state changes land during 2027. HUD still has to write construction standards for chassis-free homes, and a separate HUD proposal from June 2026 would end the chassis requirement only for upper-floor sections.
What it does not do: set any price. Realtor.com economists have said the change could reduce material costs, but no one has published a dollar estimate, and zoning still decides where these homes may go. Plan your 2027 budget on today’s prices, and treat any savings as a bonus if they reach the dealer’s sticker.
Manufactured home questions first-time buyers ask
What is the difference between a mobile home and a manufactured home?
The terms are used interchangeably, but technically a mobile home is a factory-built home made before June 15, 1976, when HUD’s federal construction code took effect. Homes built to that HUD Code since then are manufactured homes. Lenders and insurers use the official term, and many will not finance pre-1976 units.
How much is a manufactured home with land?
Realtor.com put the median listing price of mobile homes sold with land at $150,000 in September 2026. That is a resale figure, so age, size and location push individual listings well above or below it. New homes on new land cost the home price plus land and site work.
Can I use an FHA loan for a manufactured home?
Often, yes. FHA’s Title I program lends on manufactured homes with or without land, with limits set in 2024 of $105,532 for a single-section home alone and $237,096 for a multi-section home with its lot. Standard FHA mortgages also cover homes permanently installed on owned land that meet HUD’s foundation rules. A lender will confirm eligibility.
Is delivery and setup included in a mobile home’s price?
Usually the basic delivery and setup are, according to SoFi: joining the sections, connecting utilities and adding skirting. Site prep, permits, steps, porches, driveways and long-distance transport are commonly extra, so get an itemized quote that lists what is included.
Do manufactured homes lose value?
It depends largely on the land. A home on a rented lot is financed and often valued more like personal property, while one titled with land the owner holds is treated as real estate. Condition, location and local demand matter too, so look at recent resale listings in the community or area you are considering.
Three calls to make before you visit a sales lot
- The community manager, if you will rent a lot. Ask for the last five years of rent increases, what utilities and fees the rent covers, whether the park has changed owners, and if your state limits increases.
- Two lenders, one for chattel and one for mortgages. Get written rate quotes for both. If you own or can buy land, the mortgage route often decides whether the double-wide is affordable at all; our closing costs calculator estimates what a mortgage adds at signing.
- Your county planning or zoning office. Confirm a manufactured home is allowed on the parcel, what foundation it needs and what permits apply, before you pay a deposit on a floor plan.
Pricing the land, the loan and the closing
- Insurance, real estate and legal costs in 2027: the complete guide
- Cost to move a mobile home, or sell it in place
- What an acre of buildable land costs
- Who pays closing costs, line by line
- Home inspection cost and which add-ons you need
- Cost to build a site-built house, from bare lot to move-in
- House and barndominium cost calculator
- Closing costs calculator
More related guides: Tiny house costs, four buyers priced out
Pricing method: prices were researched in November 2026 for 2027 planning and may change. Figures come from the Census Bureau’s Manufactured Housing Survey via FRED (through June 2026), SoFi (May 2026), Realtor.com via Inman (October 2026), the CFPB, HousingWire (FHA Title I limits), ValuePenguin (July 2026), and 2026 reporting by KBTX, News 8000, Spotlight PA, Spectrum News and National Mortgage News. The two-buyer ledger is a hypothetical example using stated assumptions. This is general information, not financial or legal advice; confirm loan terms with a licensed lender and local rules with your county. See our disclaimer.