
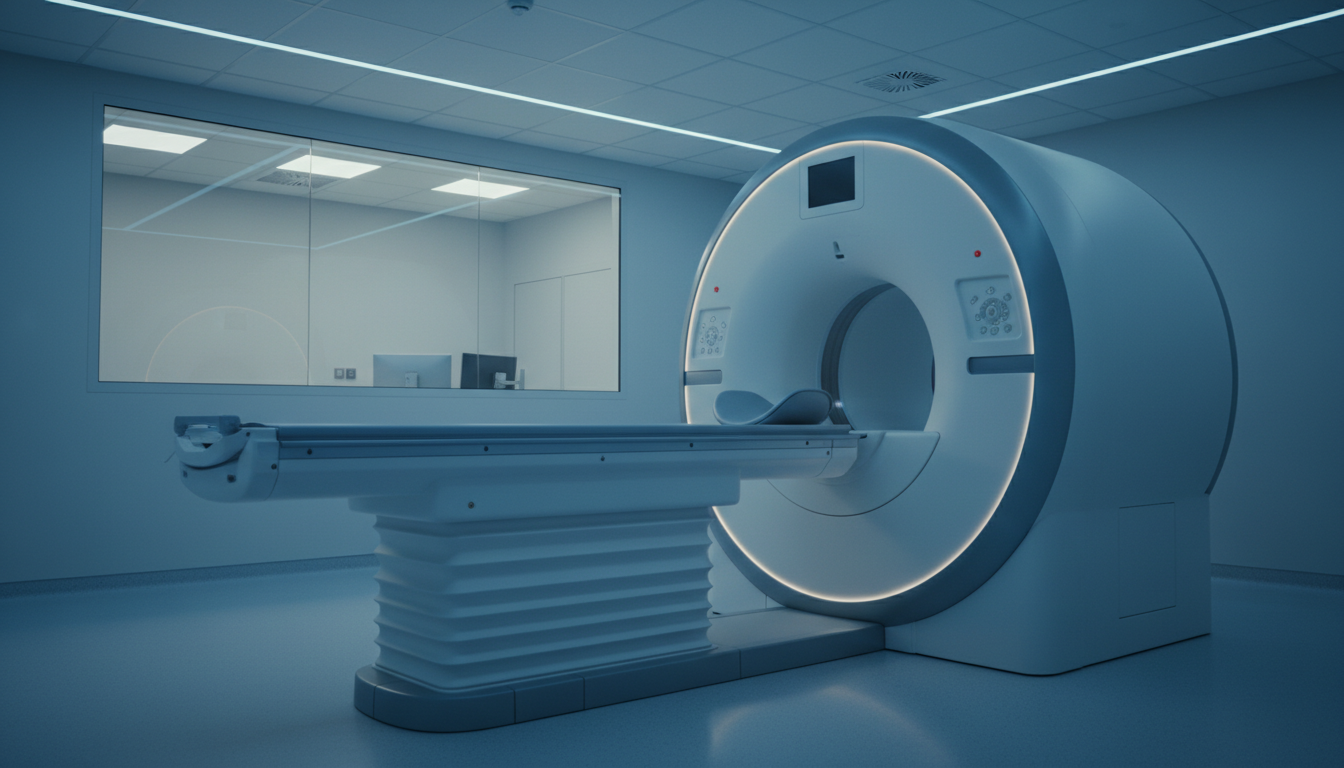
Your knee has clicked for six weeks, the orthopedist wants an MRI, and the hospital scheduler reads you a number over the phone: about $2,800. Four miles away, a freestanding imaging center lists the same non-contrast scan for $458 cash, radiologist’s read included. Across the country, an MRI without insurance usually costs $400 to $1,000 at an independent imaging center and $1,500 to $3,500 at a hospital, and the same scan can land anywhere in that span depending on where it is booked and how it is paid for.
So the body part matters less than your situation. Find yours below, then read only that section. If you want a rough number for a specific procedure first, our medical and dental cost estimator gives a starting range.
Five situations, five very different MRI bills
| Your situation | What one scan typically costs you | The move that saves the most |
|---|---|---|
| No insurance, scan ordered by a doctor | $400 to $1,000 at an imaging center; $1,500 to $3,500 at a hospital | Book a freestanding center and ask for a bundled cash price |
| Insured, deductible not yet met | Your plan’s negotiated rate, often several hundred to a few thousand dollars | Compare that rate with the cash price before you pay |
| On Original Medicare | 20% of Medicare’s rate after the Part B deductible, often well under $100 at an independent center | Choose a facility that accepts assignment |
| Ordered in the ER or during a hospital stay | Hospital pricing, folded into a larger bill | Check the itemized bill; shopping is not realistic |
| No doctor’s order: a full-body screening scan | $499 to $3,999, never covered by insurance | Ask if you need it at all |
Paying cash with no insurance
Uninsured patients have the most leverage, oddly enough, because they can buy the scan as a single product. Freestanding imaging chains and booking marketplaces post bundled prices that cover the facility, the scan and the radiologist’s report. A SimonMed location in Flagstaff, Arizona, for instance, lists a single-body-part MRI without contrast at $458 through MDsave, against an estimated national average of $900 on the same marketplace.
Hospitals post cash prices too, since federal price transparency rules require it, but they are rarely competitive. An analysis of transparency files from 274 hospitals by MedicalPriceCheck found a median cash price of $2,207 for a brain MRI without contrast, $2,124 for a lumbar spine and $2,129 for a knee. The top of the range ran past $14,000. Rural and critical-access hospitals tended to sit at the cheap end; for-profit metro hospitals at the expensive one.
You also have a legal right to a number in advance. Under the No Surprises Act, if you are uninsured or paying yourself and schedule at least three business days ahead, the provider must give you a written good faith estimate within one business day. If the final bill comes in at least $400 above that estimate, you can start a federal dispute within 120 calendar days of the bill for a $25 fee, according to CMS guidance.
- Ask what the cash price includes. MDsave’s bundles cover the facility fee and the radiologist’s interpretation. A quote that covers only the facility leaves a second bill coming.
- Confirm it is one body part. Both knees, or the neck and lower back, are two scans and two prices.
- Bring the order. A physician’s order is required for diagnostic MRI. Centers will take it by fax or in hand.
Insured, but still paying toward the deductible
This is the situation where people overpay most often, because having insurance feels like protection. Until your deductible is met, you pay the full rate your plan negotiated with that facility, and hospital-negotiated MRI rates can exceed an independent center’s cash price several times over.
The deductibles are not small. For 2027, the IRS set the minimum deductible for an HSA-eligible high-deductible plan at $1,750 for self-only coverage and $3,500 for families, with out-of-pocket maximums of $8,700 and $17,400 (Revenue Procedure 2026-24). On a plan like that, an MRI in January or February is very likely coming entirely out of your pocket.
Do this before booking: call your insurer or use its cost tool to get the negotiated rate at two or three in-network facilities, including at least one freestanding center. Then compare the cheapest of those with a cash price. If cash wins, ask your insurer whether a cash payment can be submitted toward your deductible; some plans allow it, many do not, and the answer decides whether paying cash helps you later in the year. Either way, the 2027 HSA limits of $4,500 self-only and $9,000 family let you pay for the scan with pre-tax money.
The quick test: if your plan’s negotiated rate for the scan is higher than a local imaging center’s cash price, and you do not expect to hit your deductible this year anyway, cash is usually the cheaper path.
On Medicare, where the facility still matters
Medicare sets the price, so shopping is less dramatic. Its 2026 physician fee schedule pays an estimated $195.40 nationally for a brain MRI without contrast (CPT 70551) in an independent imaging setting, before geographic adjustment. After the Part B deductible, which is $283 in 2026, you owe 20% of the approved amount, roughly $39 on that scan, or nothing if a Medigap plan picks up the coinsurance.
The same scan in a hospital outpatient department is paid under a different system and typically carries a higher approved amount, so your 20% is higher too. Medicare’s own Procedure Price Lookup tool on medicare.gov compares the two settings for specific codes, and it is worth a minute before you accept a hospital slot. CMS had not announced the 2027 Part B deductible or premium as of early November 2026; it usually does so in the fall, so check medicare.gov before scheduling a scan for January.
Medicare Advantage plans work differently: you pay the plan’s imaging copay, which is often a flat amount per scan and may require prior authorization. Read your plan’s Evidence of Coverage or call the number on your card.
Scanned in the ER or as an inpatient
Nobody comparison-shops a stroke workup, and nobody should. If the MRI happens in an emergency room or during an admission, it is billed at hospital rates and usually buried in a much larger bill. Your best tools here come afterward.
- Request an itemized bill with CPT codes. Check for duplicate scans, a “with and without contrast” code (70553) when you received no contrast, or two body parts when you had one.
- Know your surprise-billing protection. If you have insurance, the No Surprises Act generally limits what an out-of-network radiologist or ER can bill you in an emergency to your in-network cost sharing.
- Ask about financial assistance. Nonprofit hospitals are required to have a written financial assistance policy. Ask for the application before you agree to a payment plan.
- If uninsured, ask for the self-pay rate. The hospital’s posted cash price is often far below the chargemaster figure on the first bill.
Contrast, second body parts and split bills
Three things turn a $500 quote into a $1,200 one, and all three are easy to miss on the phone.
| Add-on | What it usually adds | What to ask |
|---|---|---|
| Contrast (gadolinium dye) | $200 to $500 | “Is the order with contrast, without, or both?” A with-and-without study is a different, pricier code. |
| A second body part | Roughly the price of another scan | “Is this one scan or two?” Cash bundles typically cover one body part. |
| Separate radiologist bill | Varies; can be a second invoice weeks later | “Does the price include the radiologist’s interpretation?” |
| Hospital facility fee | $500 to $1,500 or more | “Is this billed as hospital outpatient?” If so, the scan may cost more even at an off-campus building. |
That last row catches people. An imaging office in a strip mall can be owned by a hospital system and bill as a hospital outpatient department, with prices to match. The building tells you nothing; the billing status tells you everything.
No order at all: the full-body screening scan
The fastest-growing corner of the MRI market is the one no doctor ordered. Prenuvo’s posted U.S. prices run $2,499 for its Whole Body Scan, $1,199 for a Focused Scan, $799 for its brain or heart assessments and $3,999 for its Enhanced bundle. Function Health launched a $499 full-body MRI after acquiring Ezra in 2025. Insurance does not pay for any of these, and HSA eligibility is something to confirm with your plan administrator before assuming.
The bigger cost question is what happens next. Whole-body scans often find small, harmless abnormalities, and each one can lead to follow-up imaging or biopsies billed through regular insurance. The American College of Radiology has said it does not recommend total-body screening for people without symptoms. If you are considering one, discuss it with your doctor first, particularly about what the follow-up plan would be and who pays for it.
MRI price questions people ask after booking
How much is an MRI with insurance once the deductible is met?
You usually pay your plan’s coinsurance, often 10% to 30% of the negotiated rate, or a flat imaging copay. On a $1,000 negotiated rate with 20% coinsurance, that is $200. Your plan documents or insurer can give the exact figure.
Do I need prior authorization for an MRI?
Many commercial and Medicare Advantage plans require it for non-emergency MRI. Without it, the claim can be denied and the full bill can land on you. Your doctor’s office normally submits the request; confirm it was approved before the scan.
Is an open MRI more expensive?
Not necessarily. Open and wide-bore machines are often found at independent centers with competitive cash prices. Open machines may have lower field strength, so ask your doctor whether it suits the body part being scanned.
Can I get an MRI without a doctor’s order?
For a diagnostic scan, no; centers require a physician’s order. Direct-to-consumer screening companies such as Prenuvo sell scans without one, but those are elective, self-paid and not a substitute for a diagnostic MRI.
Why did I get two bills for one MRI?
Hospitals and some centers bill the facility charge and the radiologist’s interpretation separately. Both are legitimate if the price you were quoted did not bundle them. Ask the scheduler which bills to expect.
Your phone list, in order, before the scheduler books a slot
- Your doctor’s office. Get the exact CPT code on the order, whether contrast is included, and whether prior authorization has been submitted. Ask if they will send the order to a freestanding center.
- Your insurer, or Medicare. Ask for the negotiated rate at two facilities, how much of your deductible remains, and whether a cash payment would count toward it. On Medicare, use the Procedure Price Lookup.
- One independent imaging center. Ask for the bundled cash price including the radiologist’s read, and whether the location bills as a hospital outpatient department. Get it in writing as a good faith estimate.
Those three calls take about 30 minutes. For a scan whose price can swing by more than $2,000 depending on the answers, that is a good hourly rate.
Other scans and visits, priced
- CT scan cost at a hospital vs an imaging center
- What an urgent care visit costs without insurance
- Vasectomy prices by insurance type
- LASIK: the advertised price vs the two-eye total
- Eyelid surgery: when insurance covers it
- Medical and dental cost estimator
Complete guide: Healthcare Costs in 2027: A Complete Guide to What You’ll Pay
Pricing method: prices were researched in November 2026 for 2027 planning and may change. Figures come from CareRoute’s 2026 MRI cost data, MDsave provider listings, a MedicalPriceCheck analysis of hospital price transparency files, the 2026 Medicare physician fee schedule, Prenuvo’s posted prices, IRS Revenue Procedure 2026-24 and CMS No Surprises Act guidance. Actual prices vary by facility, region and plan. This is general information, not medical or insurance advice; confirm costs and coverage with your provider, insurer or Medicare. See our disclaimer.